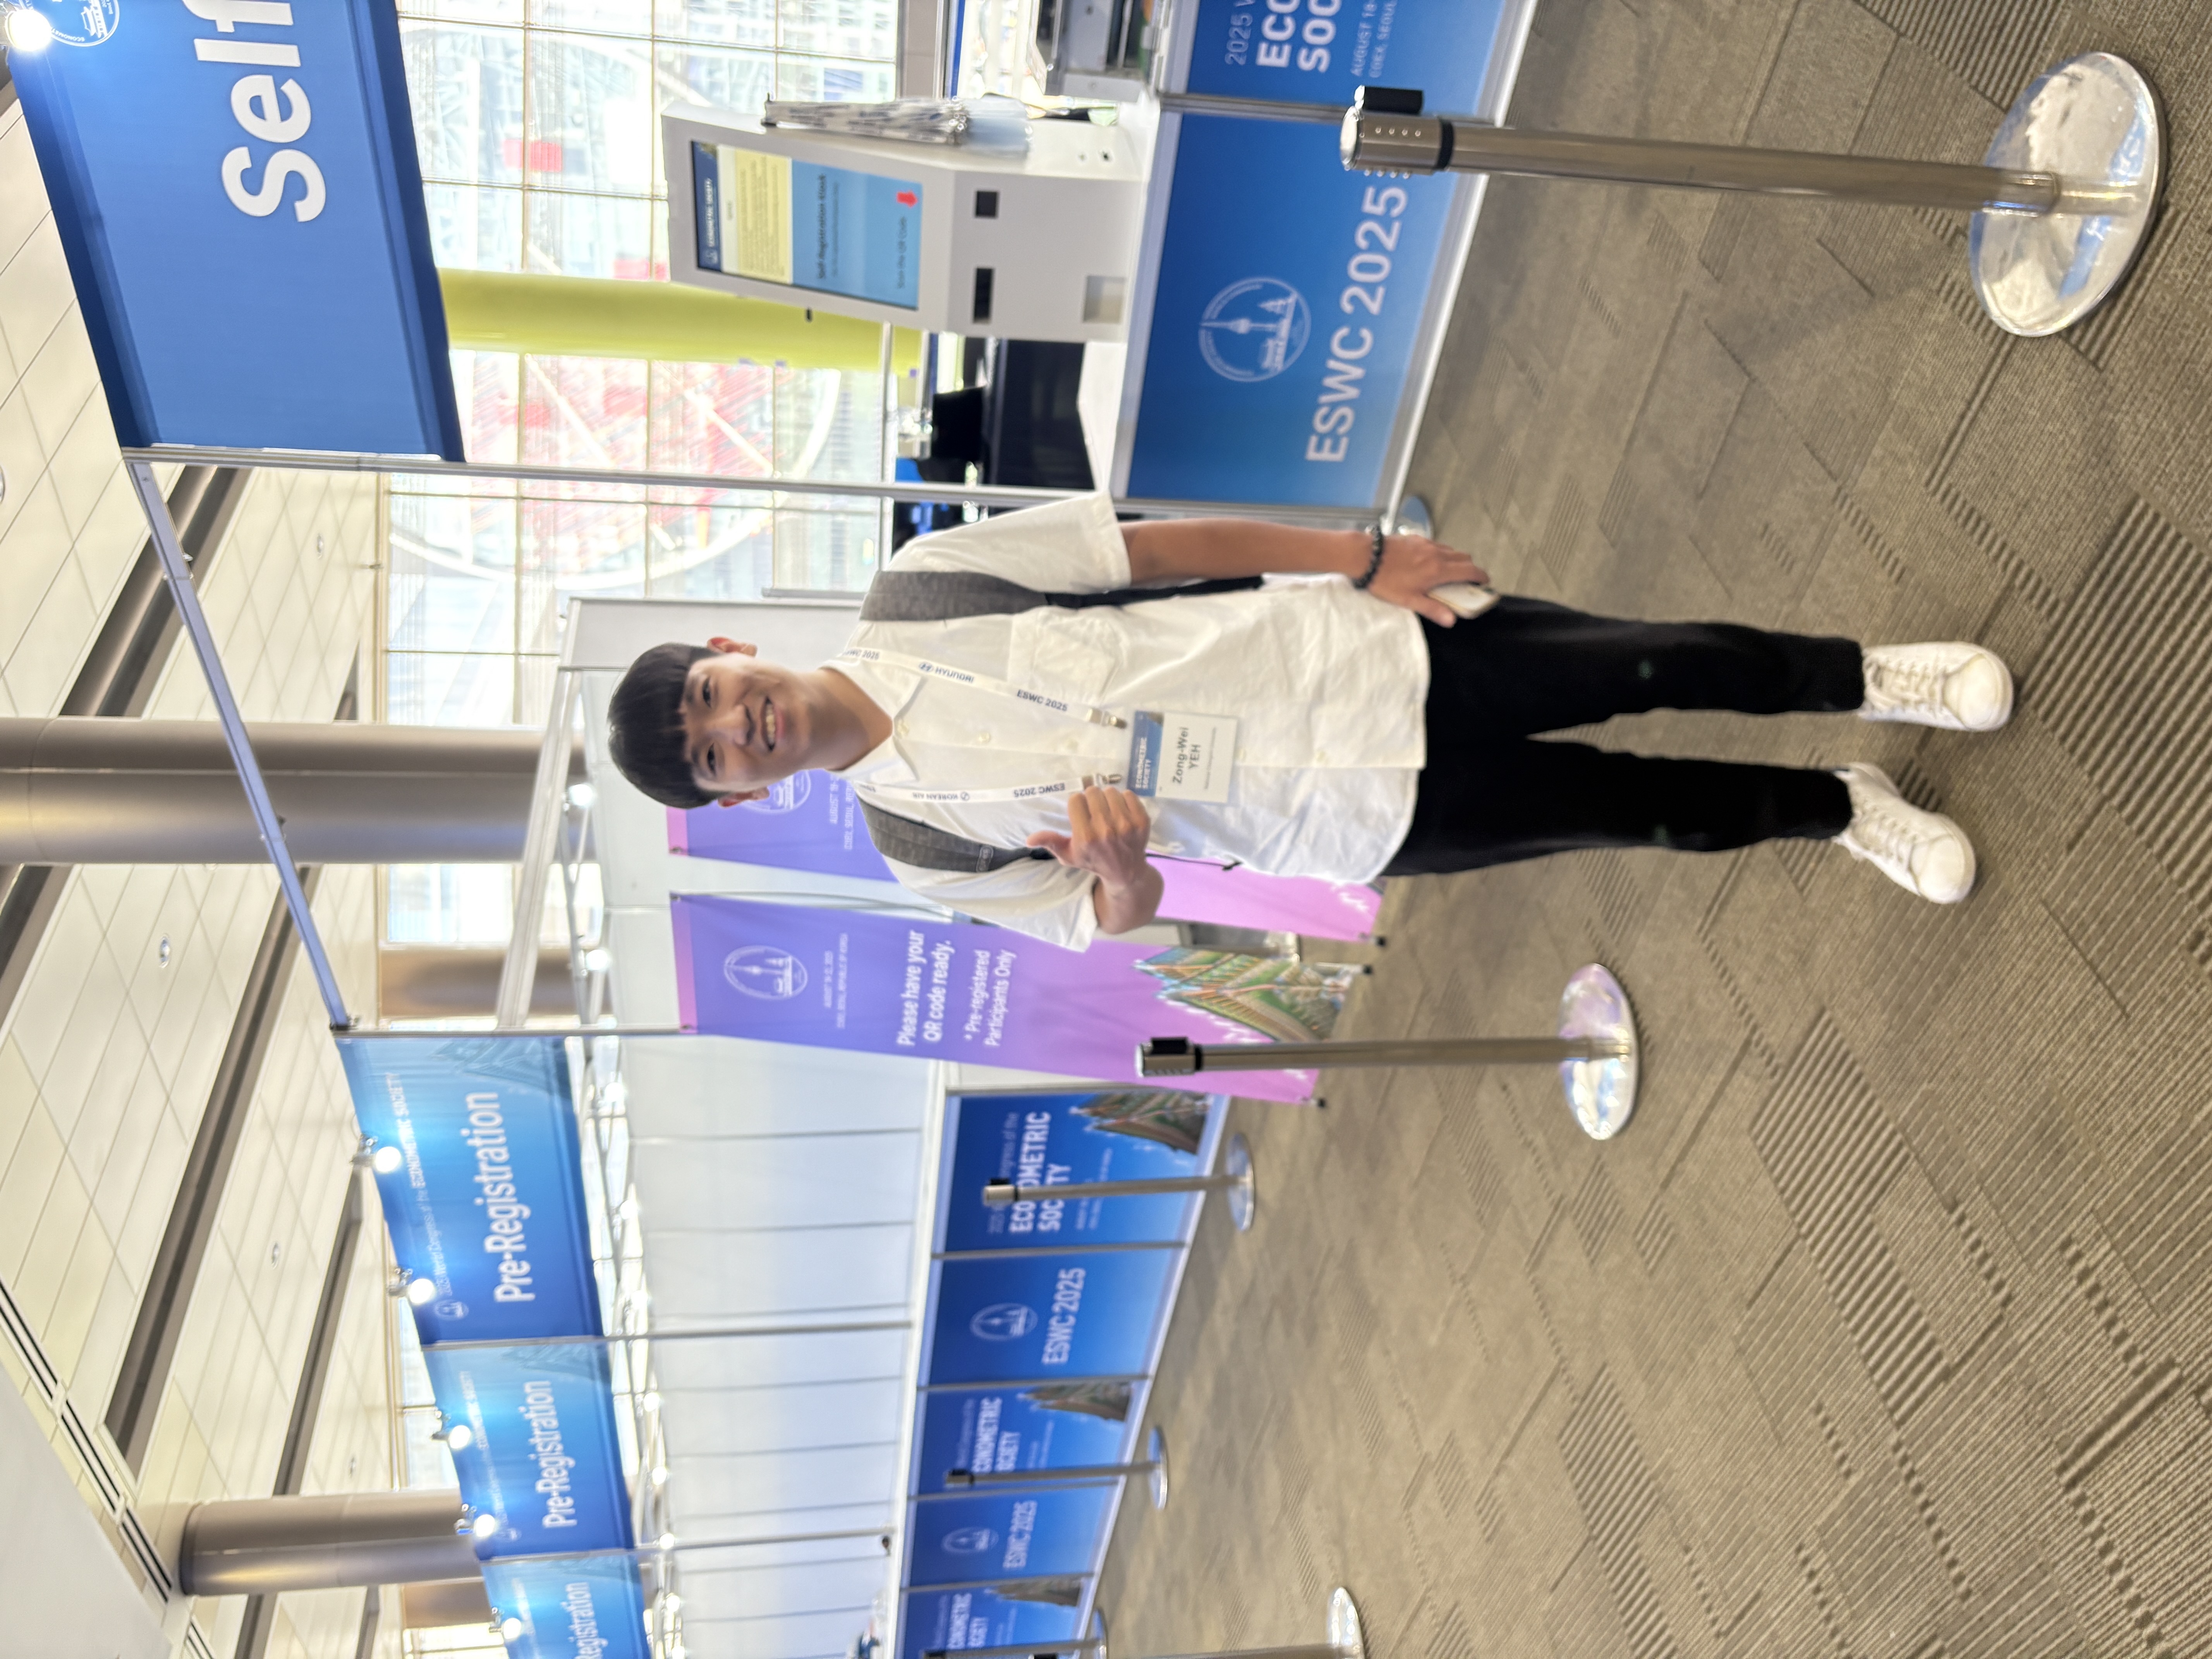
Zong-Wei Yeh

Zong-Wei (Eric) Yeh

Assistant Professor of Finance

National Chung Cheng University, Taiwan

About Me

Zong-Wei Yeh(葉宗瑋) is an Assistant Professor of Finance at National Chung Cheng University. His research focuses on Derivatives, Empirical Asset Pricing, Climate Finance, and Empirical Macroeconomics. He has published scholarly articles in journals including Pacific-Basin Finance Journal and Management Review, with additional work conditionally accepted at NTU Management Review. He teaches Statistics, Macroeconomics, and Financial Engineering.

Ph.D. in Money and Banking 2022 - 2026
National Chengchi University
M.S. in Money and Banking 2020 - 2022
National Chengchi University
B.S. in Mathematics 2016 - 2020
University of Taipei
Merit Award, TSC Thesis Award (崇越論文大賞) 2026
Best Paper Award, Manulife x Abrdn ESG Sustainability Thesis Award 2026
Conference Subsidy (ESWC), NSTC 2025
Travel Grant (CICF), NCCU 2025
Outstanding Doctoral Student Fellowship, NSTC 2022 - 2026
Gold Award, Bank of Taiwan Prize in Finance 2022
National Chung Cheng University Aug 2026 - present
Assistant Professor | Chiayi, Taiwan

Publications

Empirical Research on the Taiwan Stock Market: Review and Outlook

with Hsin Yu Chiu, Kendro Vincent, and Wei-Che Tsai

Conditionally Accepted at NTU Management Review (TSSCI)

Abstract:
Taiwan’s stock market has gained global prominence, underpinned by its leadership in the semiconductor and AI sectors. Distinguished by a retail-dominated microstructure, the market offers a unique setting for empirical finance research. This paper systematically reviews four major themes: asset pricing, anomalies, mutual funds, and investor heterogeneity. The literature reveals a definitive shift from the CAPM to advanced multi-factor frameworks, with the Fama-French six-factor and q-factor models demonstrating superior explanatory power. While traditional anomalies often appear fragile, robust abnormal returns emerge when conditioned on earnings quality, trading frictions, or machine learning signals. Mutual fund research highlights distinct stock-selection skills but persistent deficits in market timing. Furthermore, investor heterogeneity plays a central role in price formation: foreign institutions lead price discovery, whereas retail investors provide liquidity while driving sentiment-induced mispricing. Future research should leverage Taiwan’s specific institutional environment to explore non-linear factor models, AI applications, and the impact of regulatory shocks.
What Drives Jumps in the Secured Overnight Financing Rate? Evidence from the Arbitrage-Free Nelson-Siegel Model with Jump Diffusion

with Dong-Jie Fang, Jie-Cao He, and Shih-Kuei Lin

Pacific-Basin Finance Journal, 2024 (NSTC ATier 2)

Abstract:
In this paper, the arbitrage-free Nelson–Siegel (NS) model with jump diffusion (AFNSJ) is proposed to describe the Secured Overnight Financing Rate (SOFR). The parameters of this model are estimated through particle filtering conducted with a weighted maximum likelihood estimation approach. The empirical results of this study indicate that the AFNSJ outperforms the arbitrage-free NS model in fitting market data. SOFR jumps are highly related to Federal Open Market Committee meetings. Moreover, even under different interest rate changes, these jumps are mainly driven by a short-term factor. The risk adjustment term can suitably capture changes in the US Federal Reserve rate caused by the jump risk component.
Delta Hedging in the USD/JPY Options Market: Insights from Implied Stochastic Volatility

with Shih-Kuei Lin, Kendro Vincent, and Chung-Jen Lin

Management Review, 2024 (TSSCI)

Corresponding Author
Abstract:
Purpose–The purpose of this paper is to explore the performance of the implied stochastic volatility (ISV) approach in fitting the implied volatility surface (IVS) of USD/JPY and to analyze the hedging performance under standard and minimum variance (MV) delta. Design/methodology/approach–In this study, the ISV approach proposed by Aït-Sahalia et al.(2021) is mainly used to construct the IVS and parameter estimation using the Heston model as the model base. Findings–Firstly, based on the Heston model, the ISV approach has better in-sample and out-of-sample fitting ability compared to the conventional approach. On the other hand, we demonstrate that the ISV approach is effective in improving the accuracy of the hedging, especially in terms of the MV delta, using a delta-neutral hedging strategy.

Working Papers

Carbon Policy Paradox: The Divergent Impacts of Short-term versus Long-term Policies

with I-Hsuan Ethan Chiang and Shih-Kuei Lin

Presentations: CICF, ESWC, FMA, EFMA, AsianFA, MSFC, EcoSta, TFA, FeAT, TRIA, STSC

Job Market Paper Corresponding Author
Abstract:
We investigate how carbon policies with different time horizons affect fossil-fuel use. Our model shows a simple yet important mechanism: near-term tightening policies raise today’s carbon cost and slow down extraction, while long-term tightening policies push costs further into the future and encourage oil producers to extract more sooner. We use a joint affine term-structure model to uncover level and slope factors from the EUA futures curve, which capture short- and long-horizon policy signals. We find a one-standard-deviation short-horizon tightening reduces European oil supply and demand by 0.3–0.4\% within three months. In contrast, an equally sized long-horizon tightening increases both series by about 0.9\% around the six-month horizon. Furthermore, short-horizon policies shift energy use toward natural gas, while long-horizon policies crowd it out, amplifying the run-up in oil use.
Altruism in P2P Lending: Evidence from Lending Club

with Dong-Jie Fang, Chien-Hsiu Lin, and Shih-Kuei Lin

Revise and Resubmit to Review of Quantitative Finance and Accounting (NSTC ATier 2)

Presentations: EFMA, EasternFA, TRIA, TFA

Abstract:
This study examines whether altruistic language in loan descriptions affects loan funding and default in peer‐to‐peer (P2P) lending. Using 119,379 Lending Club loans, we employ text mining to construct altruistic variables, including prosocial and proenvironmental intents, and linguistic metrics, including readability, tone, and deception cues. We find that loans framed with altruistic appeals are less likely to be fully funded, yet exhibiting lower default risk. In particular, prosocial content drives the bulk of this result, whereas explicitly pro‐environmental language has a muted impact on default but appears to induce greater investor scrutiny at funding. Linguistic factors further moderate these effects: more readable and positive descriptions attract more funding and lower defaults, while more deception cues increase default risk. Overall, our findings suggest a tradeoff between altruistic signaling and credit risk. Lenders discount altruistic appeals even though such borrowers hold a lower default probability.
Implied Volatility Surface Predictability: Evidence from TAIFEX Options

with Yen-Hsun Juan and Shih-Kuei Lin

Revise and Resubmit at Pacific-Basin Finance Journal (NSTC ATier 2)

Presentations: FeAT

First Author
Abstract:
We ask which dimension of the implied volatility surface (IVS)-level, slope, or curvature-is predictable out of sample, and what information predicts it, using TAIEX index options over 213 out-of-sample months (2007--2024). We extract interpretable IVS factors via the quadratic-regression framework of Collin-Dufresne et al. (2024) and forecast their levels from a broad, economically organized set of 101 predictors using a balanced machine-learning spectrum-shrinkage, sparse, dimension-reduction, and tree-ensemble methods-each tuned by time-series cross-validation. Against a random-walk benchmark, predictability is concentrated in the slope(skew) factor, where the best models attain an out-of-sample $R^2_{RW}$ of +16.2% (p<0.01); the level and curvature are not robustly predictable. Dimension-reduction and tree-ensemble methods succeed while sparse linear models fail, and the predictive power is distributed across credit, monetary, options-microstructure, and sentiment channels. The signal is economically valuable: a conviction-weighted, delta-hedged risk reversal earns a net annualized Sharpe ratio of 1.08. The equilibrium volatility skew thus appears to be captured by methods conditioning on a distributed set of macro-financial and market state variables.
The Boundaries of Index Option Return Predictability: Evidence from Taiwan

with Pin-Chi Chen, Xian-Ji Kuang, and Tzu-Chieh Lin

Revise and Resubmit at Pacific-Basin Finance Journal (NSTC A Tier 2)

First Author
Abstract:
Out-of-sample evidence on index option return predictability comes almost entirely from U.S. data. We provide, to our knowledge, the first systematic pseudo-real-time out-of-sample evaluation of monthly delta-hedged index-option return forecasts in an Asia-Pacific market, using recursive forecasts of dividend-inclusive returns on at-the-money Taiwan index (TXO) puts over 2002–2022; the mean put premium is about −0.71% per month. What predictability we find runs through the variance risk premium, and it is episodic rather than steady. Realized stock variance (SVAR), the state variable that tracks the premium’s physical leg, is the only one of 164 candidates whose full-sample slope survives the Holm correction; its out-of-sample R² of 11.03% over the 2007–2022 evaluation window (Clark–West p = 0.008) is earned mostly in crisis months and largely disappears after 2015. In a frozen 2023–2025 holdout the decay continues: the put premium shrinks to −0.24% per month and the SVAR forecast falls behind the historical mean. Point estimates concentrate the signal in puts, though formal put–call tests cannot separate the two sides, and the incremental value of predictive timing is economically negligible. Entry-date implied variance fits the target return largely by construction, so we analyze it separately as a channel variable rather than include it in the exogenous-predictor comparisons. Same-strike puts are persistently richer than calls—a wedge that closely tracks the index-futures basis, with a near-unit slope and an economically negligible mean gap: a market-wide carry phenomenon consistent with downside-insurance demand, though alternative carry-based explanations remain open.
Beyond Emissions: Regulatory Carbon Positions and Stock Returns

with Wei-Che Tsai, Austin Liu, and Jie Luo

Submitted to Management Science

First Author
Abstract:
The allocation shortfall, the share of a firm’s verified emissions not covered by its free allowances under the EU Emissions Trading System, measures how tightly the cap binds the firm relative to the allocation the regulator grants. Among European listed firms outside the utility sector, firms whose emissions persistently fall short of their allocation earn higher subsequent returns than firms whose emissions persistently exceed it: a value-weighted spread of 5.8% per year over 2009–2024, with an alpha of 6.1% per year after the Fama–French five factors and momentum. The spread is not explained by carbon-price exposure or carbon costs, and it is concentrated among firms for which the system is economically small. Controlling for firm characteristics, low-shortfall firms subsequently beat analysts’ earnings forecasts. The evidence is consistent with investors and analysts not fully incorporating the information in firms’ regulatory carbon positions, rather than with compensation for carbon-price risk.
Soft Power Shocks: Does Attention to a Symbol Translate into Bilateral Exchange?
Single Author
Abstract:
Governments and zoos credit the giant pandas that China lends abroad with more trade, more Chinese visitors and warmer feelings toward China. We test this expectation using a soft-power shock to attention to China’s symbol. The shock comes from cub births at foreign zoos, whose timing is set by biology and involves no decision by either government. We measure each birth’s dose in the host public’s Google searches. A birth raises attention to the panda, but the attention does not convert. Searches for China, Chinese visitor arrivals, imports of Chinese consumer goods and bilateral trade show no detectable response. Trade effects of more than about 3 percent per typical birth are ruled out, against estimates of 5 to 7 percent. Political conflicts with China cut Chinese visitors and the targeted exports. Attention to a symbol stays with the symbol, while conflicts with the Chinese state move the same flows.
Intermediate-Term Reversal

with Guan-Ying Huang and Kendro Vincent

Submitted to International Review of Financial Analysis (NSTC A-)

Abstract:
Long-term reversal is widely regarded as a fragile anomaly: the premium is concentrated in small and distressed firms and does not survive the standard risk adjustment. We ask whether this verdict reflects how the overreaction is measured rather than whether it occurs. Because the overreaction is an episode in the price path rather than a condition on its endpoints, we rank stocks on the maximum drawdown - the deepest peak-to-trough decline over a window that skips the most recent year - in place of the cumulative return. The sorts uncover an intermediate-term reversal that sits between the momentum continuation and the classic long-horizon effect: the high-minus-low decile portfolio earns 1.16% per month, with an eight-factor alpha of 0.87% per month. Unlike the conventional strategy, the premium survives value weighting, persists among the stocks above the NYSE median capitalization, strengthens after 2000, and remains significant once the inference is corrected for the search across seventeen measurement horizons. It is not subsumed by momentum, the firm fundamentals, or a broad set of return predictors, and it concentrates in the stocks that are costly to arbitrage.
Volatility Decay and Arbitrage in Leveraged ETFs: Evidence from the US and Japan

with Cheng-To Lin, Shih-Kuei Lin, and George Y. Wang

Presentations: TFA, FeAT, TRIA, STSC, TWSIAM

Corresponding Author
Abstract:
While financial theory suggests that shorting bear leveraged ETFs (LETFs) is the optimal way to harvest volatility decay, we find the opposite is true in the US market. A beta-neutral arbitrage strategy shorting US bull LETFs yields a Sharpe ratio as high as 2.12, whereas the theoretically superior bear-side strategy is largely unprofitable. This paper resolves this puzzle by examining volatility decay strategies across US and Japanese markets. We find that the overall pairwise beta-neutral strategy is robustly profitable, generating highly positive skewness and offering strong downside protection. The striking cross-market asymmetry is driven not by volatility decay itself, but by the “non-compounding effect”—a friction tied to the markets’ different replication technologies (swaps in the US vs. futures in Japan). Our results show that the optimal decay, harvesting strategy is necessarily asymmetric: shorting bull LETFs in the US but bear LETFs in Japan. Finally, we develop a jump-diffusion model to provide a theoretical basis for the strategy’s exceptionally large profits during market crises.
Unspanned Reserve Adequacy and the Term Premium in Federal Funds Futures

with Dong-Jie Fang

First Author
Abstract:
The floor system separates the size of the Federal Reserve’s balance sheet from control of the policy rate. We ask whether the separation extends to the price of risk: whether the quantity of reserves is priced in the market for the policy rate. In federal funds futures, reserve adequacy, measured as reserve balances relative to GDP, is almost invisible in the current curve yet forecasts the curve’s evolution, in sample and out of sample. An arbitrage-free affine model in which reserve adequacy drives the physical but not the risk-neutral dynamics attributes about four-fifths of the variance of the twelve-month term premium to it: a one-standard-deviation decline in reserve adequacy raises the premium by 41 basis points, and the premium widens as reserves run off and narrows as they are added. The overnight market shows why. A given reserve drain moves the funds rate only when reserves are scarce, which is what gives reserve adequacy its importance; the futures curve ignores the drains and responds to the persistent state that governs their effect. The compensation embedded in federal funds futures varies with this state, rising as reserve balances approach the steep region of reserve demand.
The Price of Weather: Unspanned ENSO Risk in Commodity Futures

with Dong-Jie Fang

First Author
Abstract:
The El Niño–Southern Oscillation (ENSO) is declared by a public agency months before its economic effects arrive, and is almost invisible in commodity futures curves, yet it forecasts the returns those curves deliver. In nine commodities over 1990–2026, a 1°C higher Oceanic Niño Index lowers expected one-month excess returns on the six weather-sensitive commodities by about 16% per year, while the three metals, whose supply does not run through growing or heating conditions, show none. The predictability is concentrated in the cold season, at horizons of a few months, and in La Niña states; commercial hedgers shift their positions in the same states. A no-arbitrage model in which ENSO shifts the distribution of future prices without entering the pricing equation implies a premium that declines with maturity, a profile that the reduced-form evidence does not impose and the data do not reject. Weather is priced in commodity futures, not in the curve but in the returns.
Margin Surcharges on Out-of-the-Money TAIEX Options: Design, Verification, and Evaluation

with Yen-Hsun Juan, Chien-Hsiu Lin, and Shih-Kuei Lin

Abstract:
Taiwan's self-regulatory rules impose a margin surcharge on natural persons and non-professional institutions selling TAIEX index options: margin is raised by 20% for strikes 500 to 999 points out of the money and by 50% beyond 1,000 points. Applied in discrete steps, the surcharge can require more margin of a deeper out-of-the-money short position than of a nearer one; at current parameters a short call 1,000 points out requires 42.3% more margin than one under 500 points out. Three properties are shared by the margin rules of the United States, the European Union, Japan and the Taiwan Futures Exchange: that margin be non-increasing in moneyness, that thresholds be homogeneous of the same degree as the margin parameters, and that margin be continuous in moneyness. The current surcharge does not meet them. No surcharge varying in steps with moneyness can satisfy them; deep-tail protection must work through the floor, and a single uniform floor is the least costly way to any given level of protection. Reconstructing margins for all out-of-the-money contract-days over 2010 to 2026 at equal protection, the design satisfying the three properties lowers the largest five-day margin increase for positions 3% out of the money by 56.6%, eliminates the dominated positions found in nearly half of contract-days, and requires no more collateral, while the surcharge leaves no detectable trace on market quality. We recommend a single floor value with no moneyness thresholds; a far-month surcharge can address liquidity, separately from or together with the floor.
Learning to Fear: The Option-Implied Dynamics of Disaster Beliefs

with Bo-ai Tsai and Shih-Kuei Lin

Presentations: FeAT

First Author
Option-Implied Probability Distortions and Stock Return Predictability

with Ting-Xuan Wang, Wei-Yu Kuo, and Shih-Kuei Lin

Presentations: TFA, FeAT, PBFEAM

Abstract:
As retail investors increasingly influence financial markets, understanding how cognitive biases affect asset prices is crucial. This study examines the return predictability and economic value of the curvature parameter of probability weighting function, which captures investors’ risk perception through probability distortions. Using a empirical pricing kernel approach with particle filtering, we construct a Probability Weighting Index (PW I) and analyze its predictive power. Empirical results suggest that PW I exhibits a certain degree of predictive power, provides incremental information beyond traditional predictors, and offers economic value through an investment strategy that outperforms the buy-and-hold approach. Further analysis indicates that PWI primarily predicts returns through the discount rate channel, distinguishing it from sentiment-based predictors. Our findings highlight the role of cognitive biases in asset pricing by introducing PW I as a potential behavioral-based predictor.
Risk Converge and Procyclicality in Futures Margin System: Evidence from Taiwan Stock Exchange Index Futures

with Ting-Da Yan, Ting-Fu Chen, and Chien-Hsiu Lin

First Author
Abstract:
Central counterparty (CCP) margin models face a fundamental trade-off between risk coverage accuracy and procyclicality. This study quantifies this trade-off by evaluating four distinct margin systems applied to Taiwan Stock Exchange Index (TAIEX) futures data. The models are constructed from combinations of Simple Moving Average (SMA) and Heston (1993) volatility estimators, specifications with Value-at-Risk (VaR) and Expected Shortfall (ES) risk measures. Our results show that while the Heston model achieves superior backtesting accuracy, it induces substantial procyclicality, generating more volatile and unstable margins than the SMA model. Across all specifications, ES consistently provides more robust protection against extreme tail losses. These findings highlight a critical dilemma for regulators, as the pursuit of statistical accuracy may introduce systemic instability. The incumbent SMA model, while less precise, possesses valuable stabilizing properties, suggesting that the choice of a margin model is a substantive policy decision involving competing objectives.
Do Investors Care About Carbon Higher Moment Risks
Single Author
Abstract:
TBA

Research Grants

Unspanned Reserve Adequacy and the Term Premium in Federal Funds Futures

Principal Investigator · National Science and Technology Council (NSTC), Taiwan

November 2026 – October 2027

Get in Touch

Office Address National Chung Cheng University
No. 168, Sec. 1, University Rd., Minxiong Township, Chiayi County 621301, Taiwan
Phone (+886) 981-897-609

Feel free to reach out for research collaborations or to request my full CV.

Download Full Resume